When you hear “The Federal Reserve raised interest rates,” it sounds like bad news—especially if you’re going through a divorce and trying to figure out what happens to the house.
But it’s not quite that simple.
Think of the economy like a car going too fast. Inflation means prices are rising too quickly. One of the Fed’s tools to slow things down is raising the rate banks pay to borrow money overnight.
That can make borrowing more expensive throughout the economy.
But here’s something many people don’t realize: The Fed does NOT directly set mortgage rates.
Mortgage rates are influenced by the bond market, inflation, the economy, and what investors believe will happen next.
So why could a Fed rate increase eventually be helpful?
Because one reason the Fed raises rates is to fight inflation. If inflation begins coming down, longer-term interest rates—including mortgage rates—could eventually improve.
And that can matter A LOT during a divorce.
Higher mortgage rates can reduce what buyers can afford. That may mean fewer buyers competing for homes, slower home sales, and potentially less pressure pushing home prices higher.
For a divorcing couple, that can change the numbers in several ways.
Maybe one spouse wants to keep the house and needs to refinance to remove the other spouse. Maybe the house needs to be sold. Maybe both spouses need to qualify to purchase new homes after the divorce.
The interest rate, home value, equity, support payments and wording of the divorce decree can all affect what is possible.
That’s why the house shouldn’t be an afterthought in a divorce.
Before agreeing that “she keeps the house,” “he refinances within six months,” or “we’ll just sell it,” it makes sense to find out whether the plan actually works financially.
Sometimes waiting could help. Sometimes acting sooner makes more sense. And sometimes a small change in how the mortgage or divorce agreement is structured can make a major difference.
Don’t Make a $300,000, $500,000 or $800,000 Housing Decision Based on a Guess.
I’ve been in the mortgage business since 1999, and I help divorcing homeowners understand their mortgage options before important decisions become permanent.
If you are going through a divorce—or you’re an attorney, mediator or real estate professional working with someone who is—give me a call.
Let’s look at the numbers before you decide what happens to the house.
About the Author
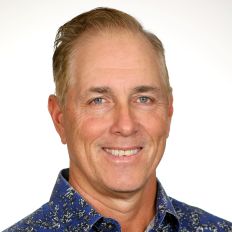
Dave Jamison is a divorce mortgage strategist and co-owner of Rainbow Mortgage Inc., an independent mortgage brokerage licensed in Minnesota, Florida, and North Dakota. With more than 26 years in residential lending—including 13 years as an underwriter for Fortune 500 mortgage institutions—Dave brings deep, practical expertise to complex divorce-related real estate matters.
What sets Dave apart is his underwriting foundation. Rather than approaching cases from a sales perspective, he evaluates them through the lens of how loans are actually approved—income calculations, debt ratios, reserve requirements, and documentation standards. This allows him to assess feasibility early in the divorce process, helping prevent refinance provisions that later fail and ensuring agreements align with real-world lending guidelines.
Dave and his wife, Gale, founded Rainbow Mortgage Inc. in 1999, initially serving borrowers with complex financial situations. In 2004, he began specializing in divorce mortgage planning, applying his expertise to support attorneys, mediators, and financial neutrals. Since then, he has spent more than two decades helping collaborative teams structure realistic refinance timelines, evaluate buyout options, and avoid post-decree mortgage breakdowns.
He is particularly skilled in analyzing self-employed income, support income, and multi-property scenarios—areas where legal and financial assumptions often diverge from underwriting standards. Known for his calm, direct, and non-adversarial approach, Dave provides clear, objective guidance that supports durable agreements.
David Jamison
Rainbow Mortgage, Inc.
Ph: 952-405-2090
www.RainbowMortgageInc.com